
Your Child Already Has a Trump Account: Here's How to Claim the $1,000
Your child may already have a Trump Account and you might not even know it. On October 1, 2026, the Treasury Department automatically enrolled tens of millions of eligible children in brand new tax-advantaged savings accounts, each potentially carrying a $1,000 government deposit. Here is what Trump Accounts are, what just changed, who qualifies for the money, and what employers need to know before year end.
- What Are Trump Accounts (Section 530A)?
Trump Accounts are individual retirement accounts created under Section 530A of the tax code by the 2025 One Big Beautiful Bill Act. They are tax-deferred savings accounts for U.S. citizen children under age 18. They are not Roth IRAs and they are not 529 education plans.
The child is the account beneficiary and the money belongs to the child, not the parent
A parent, guardian, or authorized responsible party manages the account while the child is a minor
The years before the child turns 18 are called the growth period, with special contribution, investment, and withdrawal rules
After the growth period ends, the account is generally governed by ordinary traditional IRA rules
2. What Just Changed: Automatic Enrollment Began October 1, 2026
On September 30, 2026, Treasury and the IRS issued temporary regulations (T.D. 10056) giving the Treasury Secretary authority to establish Trump Accounts automatically for eligible children who did not already have one.
- On October 1, 2026, Treasury automatically created auto accounts for eligible children, with more to be established periodically
- Treasury estimates about 73 million eligible children in 44 million families, and expects more than 60 million new accounts in 2026 alone
- Before auto-enrollment, only a few million families had opened accounts, since parents had to file Form 4547 themselves
- Auto accounts hold investments through a master group trust until claimed by an authorized person
In plain terms: if your child is eligible and you never signed up, the government likely opened the account for you this month.
- The $1,000 Pilot Deposit: Who Qualifies and How to Claim It
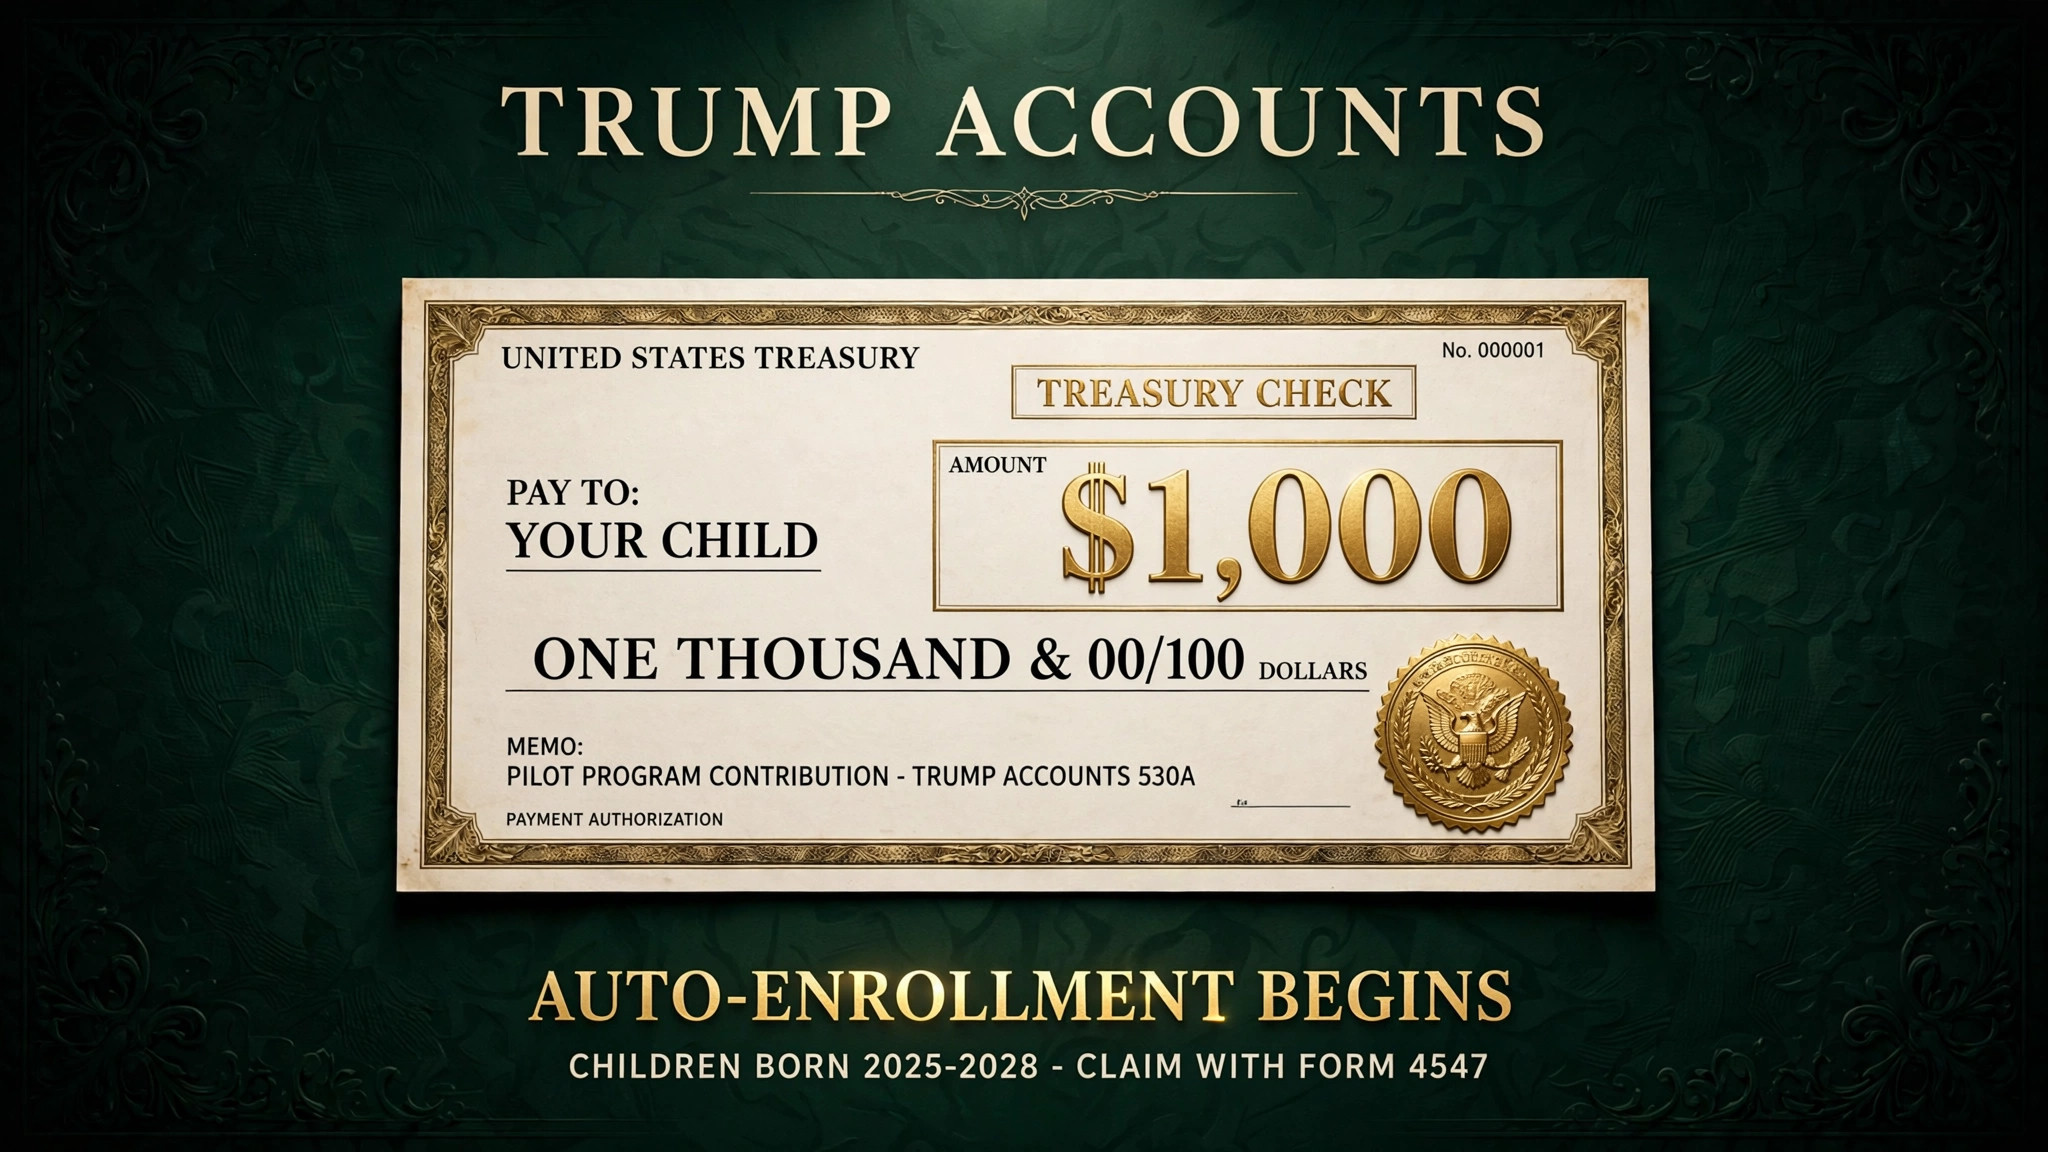
The law provides a one-time $1,000 government contribution for each U.S. citizen child born between January 1, 2025 and December 31, 2028, with a valid Social Security number, as confirmed by the IRS pilot program guidance.
- The deposit is not automatic with the account: a parent, guardian, or eligible individual must make the required election using Form 4547, Trump Account Election(s)
- An auto account must first be claimed through an electronic identity verification process before it can receive the $1,000 deposit or any family and employer contributions
- The pilot is temporary: it covers 2025 through 2028 births unless Congress extends it
If you have a young child, claiming the account is the step that unlocks the $1,000.
- Contribution Rules: $5,000 Annual Cap and $2,500 Employer Contributions
Annual non-deductible cash contributions are capped at $5,000 per child (indexed for inflation) before the beneficiary turns 18. IRS guidance on employer contributions sets the employer framework.
- Employers can make tax-preferred contributions of up to $2,500 per year (indexed) for an employee or the employee’s dependent
- Employees may also be able to contribute pre-tax to a dependent’s account through an employer cafeteria plan under Treasury guidance
- Individual family contributions are made with after-tax dollars, so there is no deduction for parents contributing directly
- Employer contribution programs must be separate written plans that satisfy nondiscrimination requirements
For business owners, the $2,500 employer contribution is the piece to model in 2027 benefits planning.
- Growth Period Rules: Index Funds Only, No Withdrawals Before 18
While the child is under 18, Trump Account funds may only be invested in eligible investments: mutual funds or ETFs tracking a U.S. equity index, with annual fees of no more than 0.1 percent, per IRS proposed regulations.
- By default, funds are initially invested in a broad U.S. stock market index fund such as the State Street SPDR Portfolio S&P 500 ETF
- Withdrawals are generally not allowed before the year the child turns 18
- The accounts cannot hold cash, money market funds, or individual stocks during the growth period
- Like any market investment, the account value can fall as well as rise; the $1,000 deposit carries no guaranteed return
Think of it as a long runway: the money grows in the market for up to 18 years before the child can touch it.
What Should Your Business Do Now?
- Parents: check whether your child was auto-enrolled and complete the claim process with identity verification so the account can receive the $1,000 deposit and contributions
- File Form 4547 for any eligible child born 2025 through 2028 to secure the pilot deposit election
- Business owners: model the $2,500 per-employee employer contribution in your 2027 benefits review and talk to your payroll provider about cafeteria plan options
- Do not confuse Trump Accounts with 529 plans or Roth IRAs: the contribution limits, tax treatment, and withdrawal rules are different
Do these now, and the new program becomes an advantage instead of paperwork you missed.
How Funds to Function Can Help
This is the work we do every day at Funds to Function. A brand new federal program with auto-enrollment, pilot deposits, and employer contribution rules is exactly where families and businesses need a steady guide. That is what we do.
- Family tax planning: we review your children’s eligibility, walk you through claiming auto accounts, and make sure Form 4547 elections are filed correctly for the $1,000 deposit.
- Employer benefits planning: we model the $2,500 tax-preferred employer contribution for your 2027 benefits package and coordinate with your payroll setup.
- Small business advisory: we explain how Trump Accounts interact with your existing retirement and benefits offerings, so nothing overlaps or gets missed.
- Bookkeeping and payroll: our bookkeeping and payroll team keeps contribution records clean and IRS ready from day one.
One short conversation is all it takes to know exactly where your family and your business stand.
Book your free 15 minute consultation with us: calendly.com/fundstofunction-info/15min
This article was published by Funds to Function. Visit us at www.fundstofunction.com.
Disclaimer
The information shared in this article is for educational and informational purposes only.
While Funds To Function, LLC ensures accuracy from reliable sources, readers should verify details independently before applying them to personal or business decisions.
Funds To Function, LLC is not responsible for any actions taken based on this content, it is provided solely to enhance your knowledge.


Leave A Comment